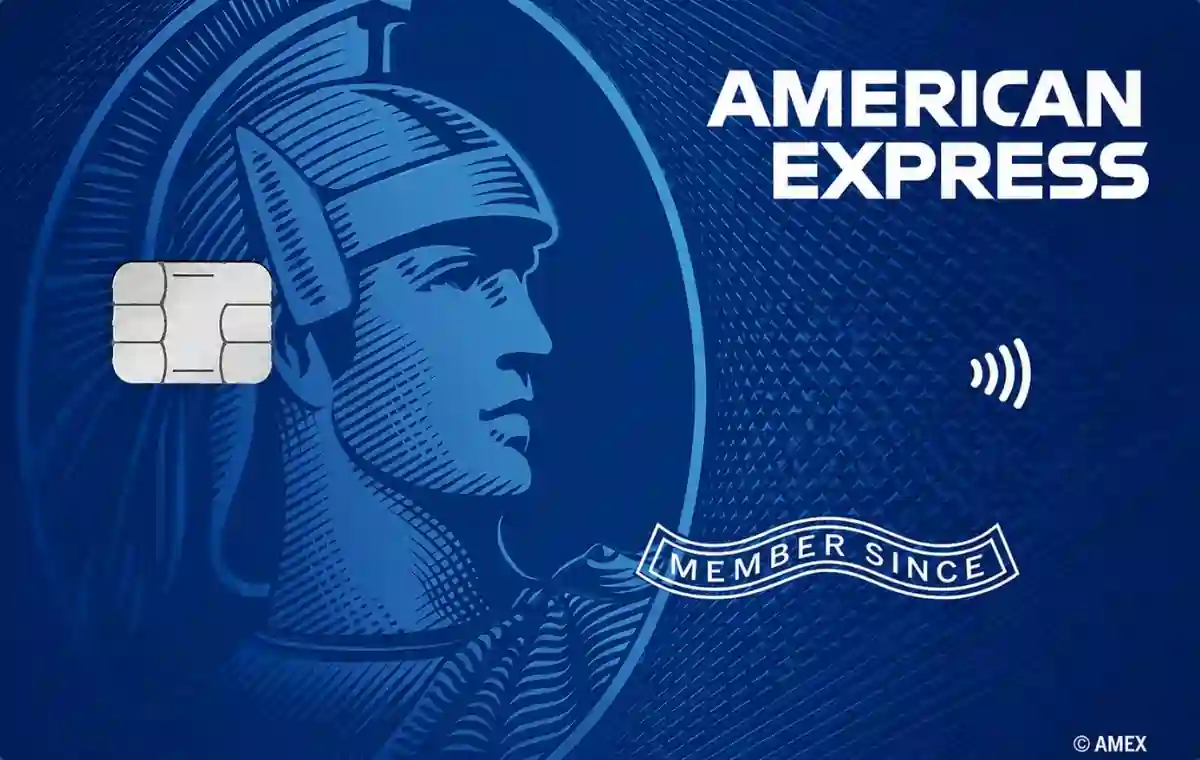
American Express SmartEarn™ Credit Card
The American Express SmartEarn™ Credit Card is an entry-level card designed for beginners and young professionals. It offers accelerated reward points on popular everyday platforms like Zomato, Uber, and Flipkart.
Overview
- 1
First-time credit card users looking to enter the American Express ecosystem.
- 2
Young professionals who frequently spend on food delivery, cabs, and online shopping.
- 1
Earn ₹500 cashback as statement credit upon spending ₹10,000 or more within the first 90 days of card issuance.
Reward Rate
- 1
Get a ₹500 voucher on reaching an annual spend of ₹1,20,000.
- 2
Get another ₹500 voucher on reaching an annual spend of ₹1,80,000.
- 3
Get another ₹500 voucher on reaching an annual spend of ₹2,40,000.
Benefits
Fuel Waiver
Dining Benefits
Fees & Charges (excluding GST)
Fee Waiver: ₹40,000 annual spends
Transaction Costs
Late & Cash Fees
Hidden Catches & Exclusions
- 1
Low accelerated rewards cap: The 10X and 5X accelerated points have very strict monthly limits. You max out the 10X Zomato cap after spending just ₹2,500 in a month, and the Amazon 5X cap at ₹2,500. Once you cross these low thresholds, spends revert to the base 0.5% rate.
- 2
Reward exclusions: Base reward points are strictly excluded on utilities, fuel, insurance, rent, education, wallet loading, and government payments.
- 3
Acceptance Issues: Amex network acceptance in India is robust online, but offline acceptance remains relatively lower in tier-2 and tier-3 cities compared to Visa or Mastercard.
Eligibility
You must have an active Indian bank account, a clean credit history with no defaults, and ideally reside in an Amex-serviceable tier-1 or tier-2 city.
Expert Analysis
- 1
Best use cases: Using it strictly for small monthly micro-transactions on Zomato, Uber, Flipkart, and Amazon up to ₹2,500 each to perfectly capture the 10X/5X accelerated reward caps.
- 2
Who should get this card: Students with part-time incomes, first-jobbers, or anyone looking to build a credit history and establish a relationship with American Express at the lowest possible entry cost.
- 3
Who should avoid it: High spenders, frequent travelers expecting lounge access, and users who want a simple card for paying utility and rent bills (as these yield zero points).
- 4
Realistic reward expectation: If optimized strictly around the 10X partner caps, you can achieve a solid 5% return. However, if used as a primary card for heavy shopping, the overall reward rate drops dramatically closer to the 0.5% base level due to the low monthly limits.
- 5
Comparison positioning in its segment: The SmartEarn card competes with the SBI SimplyCLICK, Axis ACE, and HDFC Millennia. While competitors offer better uncapped flat cashbacks (like Axis ACE's 2% base) or much higher limits on 5% partner cashbacks (like HDFC Millennia), the SmartEarn card wins on having the most easily achievable fee-waiver limit (₹40,000) and entry into the premium Amex customer service ecosystem.
You might also like
Cards similar to American Express SmartEarn™ Credit Card